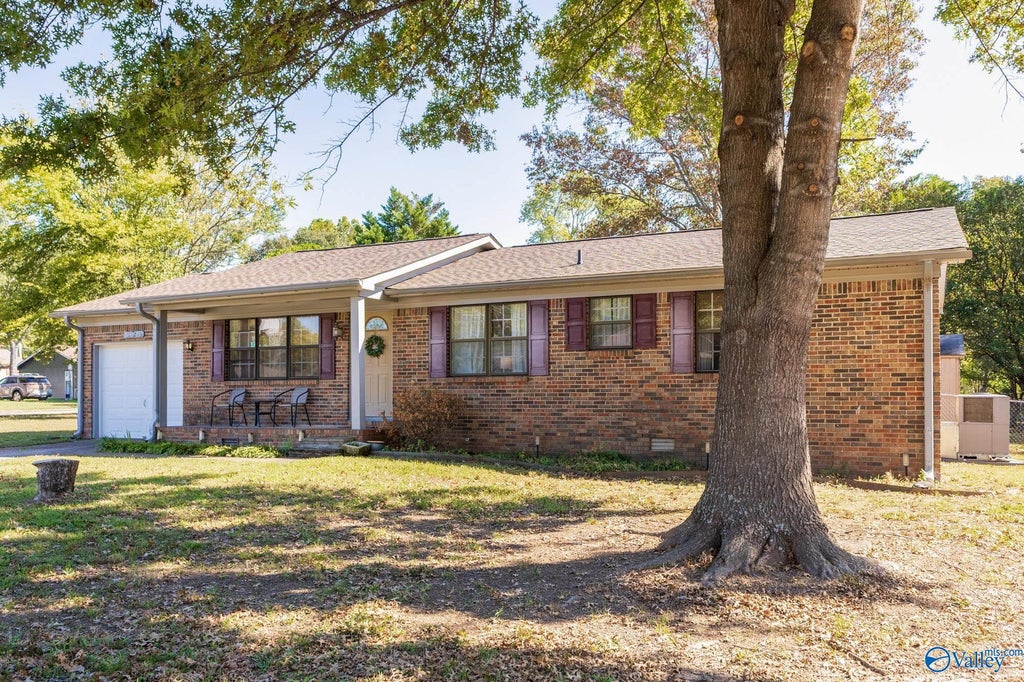
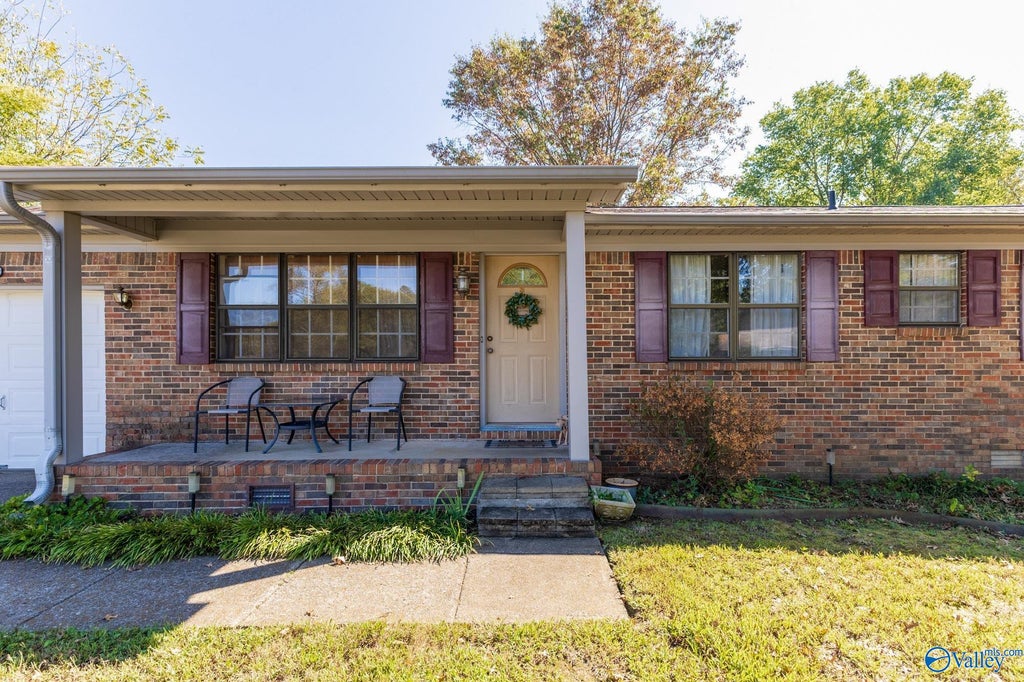
24614 Silent Spring Dr
Athens, Alabama 35613
A full brick rancher in Fieldstone with room to spread out: engineered wood floors, trey ceilings, a roof and water heater already replaced, a fenced backyard, and no HOA. The seller is motivated, and eligible VA buyers may be able to assume the existing VA loan. Laura also has a second listing in Huntsville, further down this page.

Alabama License #000160593
See it before you drive over
Real photos from the listing itself, not stock. Laura can walk you through the full ValleyMLS gallery for this home, room by room.
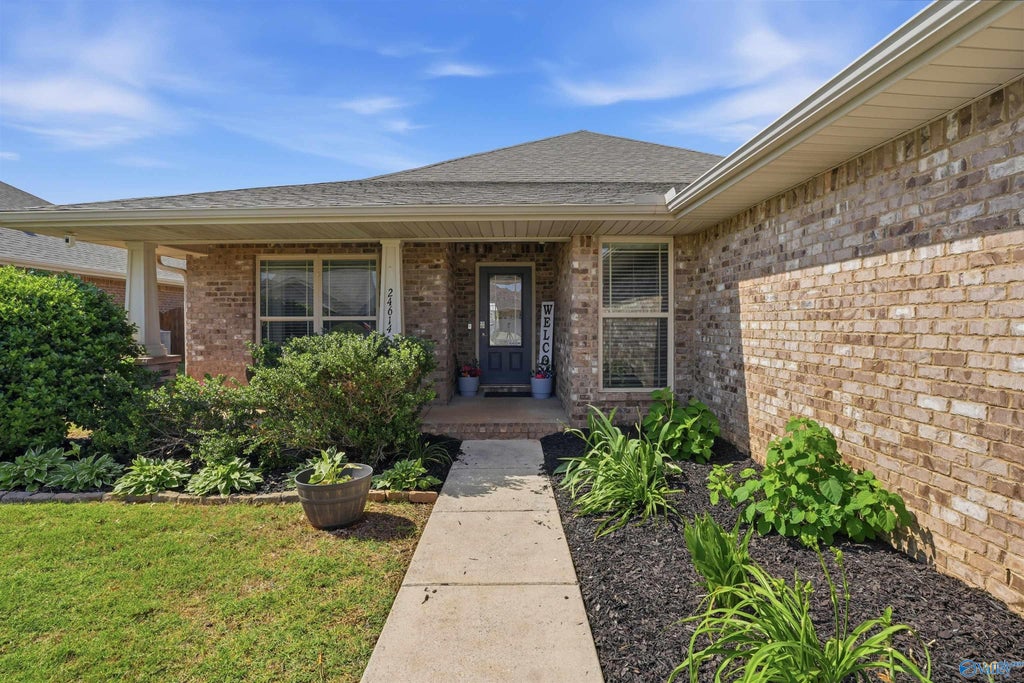
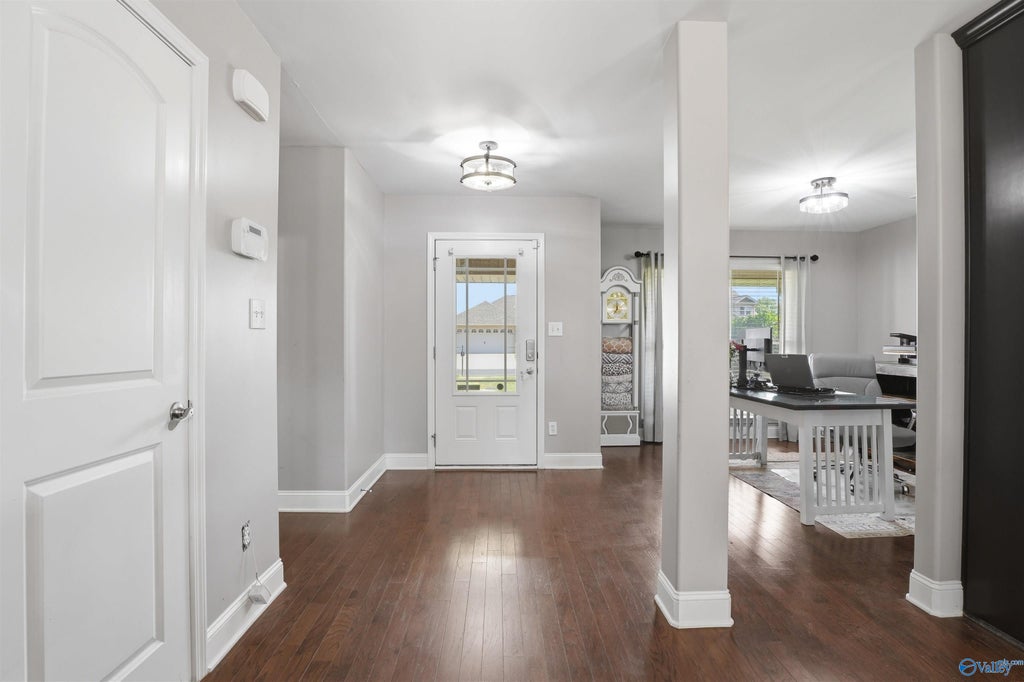
Full brick. No HOA. And a VA loan a buyer may be able to assume.
The listing leads with two words buyers in Athens listen for: motivated seller. Behind that is a 2013 full brick ranch in the Fieldstone subdivision, in the Athens City School district, with the expensive items already handled: a new roof in 2023 and a new water heater in 2024. And there is no HOA, so no association fees and no committee telling you what you can do with your own yard.
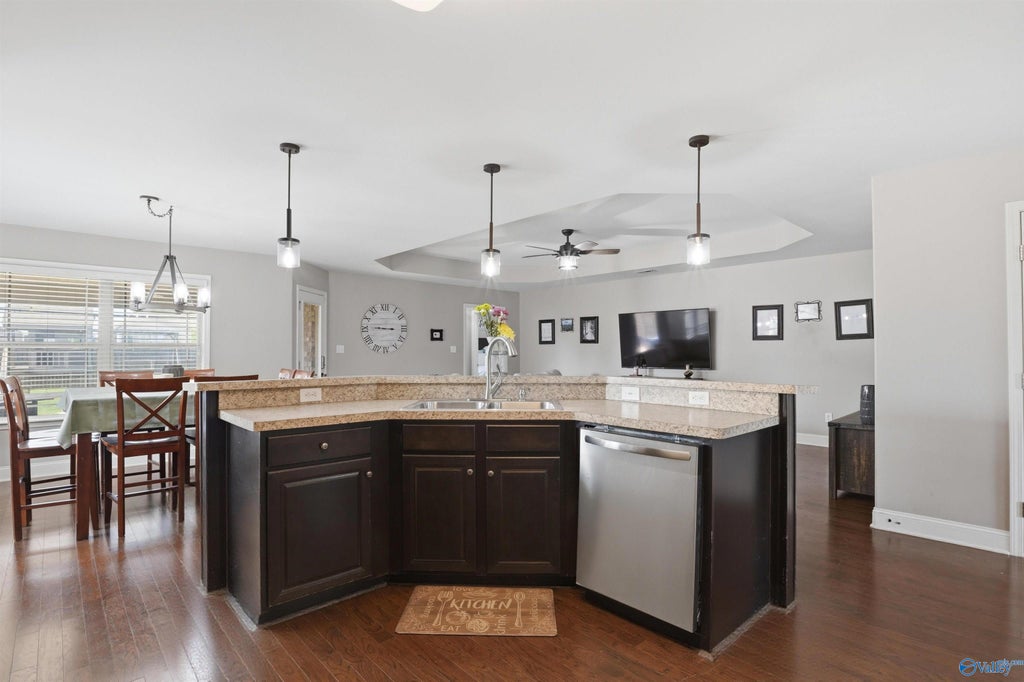
Inside you get engineered wood floors through the living areas and kitchen, new carpet in three bedrooms, updated light fixtures, and trey ceilings in both the great room and the primary bedroom. The kitchen runs stainless steel appliances, including a dishwasher installed in 2024. Out back, the yard is fenced and ready for entertaining, pets, or play.
- VA loan assumable for eligible buyers, per the listing; ask Laura how the assumption works on this home
- New roof in 2023, new water heater in 2024, new dishwasher in 2024
- No HOA, in the Athens City School district, Fieldstone subdivision, Limestone County
- Full brick ranch, one story, built 2013, 0.27 acre lot
- Engineered wood floors in the living areas and kitchen, new carpet in three bedrooms
- Trey ceilings in the great room and the primary bedroom, updated light fixtures throughout
- Kitchen: stainless steel appliances and room to cook for a crowd
- Fenced backyard, ready for entertaining, pets, or play
Kitchen and great room at 24614 Silent Spring Dr. Photo from the ValleyMLS listing gallery for 24614 Silent Spring Dr (MLS #21928982), checked November 12, 2026.
A fenced backyard, Athens City Schools, and no HOA.
Room to entertain, garden, and play, with Athens City Schools for the kids and easy Athens and Huntsville access for work. Full brick, one story, and a seller the listing calls motivated.
Come See It in Person1124 Danmann Dr SE, Huntsville
A brick ranch on a corner lot in south Huntsville, priced for a first home or a smaller footprint, with the big updates already done.
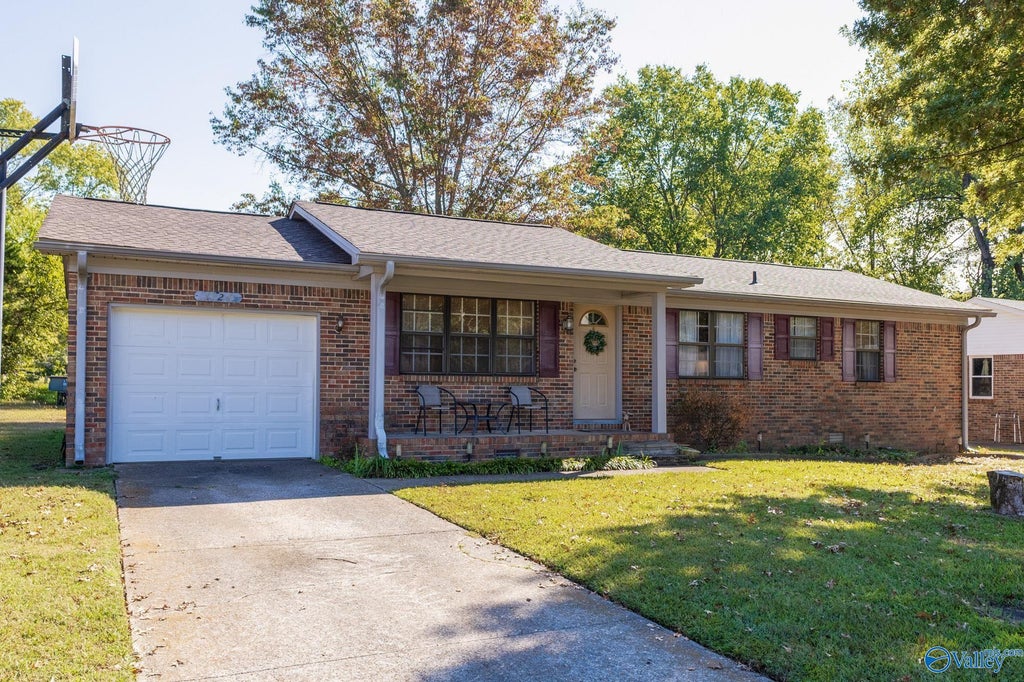
Welcome to Mountain Gap Estates. This ranch style home offers 3 bedrooms, 2 bathrooms, and 1,109 sq ft of comfortable living space on a 0.35 acre corner lot. The backyard is fenced, with room to enjoy the outdoors, entertain, or let the pets play. An attached one car garage adds everyday convenience, and a 10x12 storage shed gives you space for tools and lawn equipment.
The major updates are recent: a new roof in 2024, heating and cooling replaced in 2022, and a water heater that is about four to five years old. The home sits a short distance from Mountain Gap School, Publix, and the Aldridge Creek Greenway.
- New roof in 2024, heating and cooling replaced in 2022
- 0.35 acre corner lot, fenced backyard, 10x12 storage shed
- Attached one car garage, full brick, one story
- Close to Mountain Gap School, Publix, and the Aldridge Creek Greenway
- The listing itself advertises a 1/0 rate buydown offered by a preferred lender; ask Laura how it works on this home
- On this page's math, at $229,000 with 10% down and a 7.25% note rate, the full principal and interest payment is $1,406 a month, and a 1/0 buydown payment in Year 1 is $1,269, saving $137 a month
A $2,000 lender credit, plus the 2/1 buydown run on the Athens home
Two separate levers, and you can use both. The credit comes from the lender side. The buydown is a payment strategy. Here is how each one works, in plain English, with the real numbers on this home.
Finance either of these homes with Oliver Ames at Swift Mortgage, Laura's lending partner, and a $2,000 lender credit is applied on your side at closing. Point it at a buydown, or point it at your fees. It is your credit, so it is your call.
Put it toward a buydown
Fund part of a temporary buydown escrow and start in this home with a lower payment for the first year or two, stepping up on a schedule you see in writing before you sign anything.
Put it toward your fees
Skip the buydown and apply the same $2,000 to your closing costs and fees instead. Same credit, less cash out of pocket on closing day, applied at closing and never paid as cash back.
The 2/1 buydown, explained plainly
A temporary buydown lowers your payment for the first two years. Your note rate does not change. The difference is prepaid into an escrow account at closing and escrow tops up each payment. It is not something you do because you have to. It is an option you use because you can.
On a 7.25% note rate, your payment is calculated at 5.25% for the first 12 months.
Your payment steps up to a 6.25% calculation for months 13 through 24.
Your payment settles at the full 7.25% note rate for the rest of the loan. If you refinance early, unused buydown escrow typically applies to your loan balance.
The 2/1 math on 24614 Silent Spring Dr, run for you
At the $332,000 price with 10% down and a 7.25% note rate, the loan is $298,800 and the full principal and interest payment is $2,038 a month. A 2/1 buydown saves $388 a month in Year 1 (a $1,650 payment at 5.25%) and $199 a month in Year 2 (a $1,840 payment at 6.25%). Funding the full two years costs $7,043, which is 2.12% of the price.
That fund can be built more than one way, from seller concessions negotiated in the offer, from the $2,000 lender credit above, or from a combination. The credit alone covers the first $2,000 of that fund, leaving $5,043 to come from seller concessions or another mix. Oliver runs the exact structure with your real quote and checks it against the loan program limits before any offer goes in, so there are no surprises at the closing table.
VA buyer? Ask about the assumable loan on the Athens home
The Silent Spring listing advertises a VA assumable loan for eligible buyers. An assumption means an eligible buyer takes over the seller's existing VA loan instead of opening a brand new one, subject to VA eligibility and servicer approval. The existing loan's rate and balance are not published on this page, so ask Laura for the current figures and how an assumption would run on this home.
Plain English, no jargon wall
A first home in Athens, a VA buyer near Redstone Arsenal, and a buyer who needs help with the down payment do not all fit the same loan. These are the main paths.
Conventional
The standard loan for buyers with solid credit. As little as 3% to 5% down for a primary home.
- Best pricing usually at 20% down, with no mortgage insurance
- Works for primary homes, second homes, and investment homes at different down payments
- Gift funds and seller concessions allowed within program limits
FHA
A flexible option with 3.5% down and more forgiving credit guidelines.
- Popular with first time buyers across North Alabama
- Upfront and monthly mortgage insurance apply
- Seller can help with closing costs within FHA limits
VA
For eligible veterans, active duty service members, and surviving spouses.
- Zero down for most eligible buyers
- No monthly mortgage insurance
- A funding fee applies unless the veteran is exempt
USDA
Zero down for eligible rural areas and income qualified buyers. Parts of Limestone County and the edges of Madison County can be USDA eligible, so every address must be checked, and homes further out often are.
- Zero down when the home and household income qualify
- Address and income limits apply, so ask before you assume
- A good fit for full time homes outside the bigger metros
Down Payment Assistance
Alabama programs that help with the down payment and closing costs, so a buyer does not have to wait years to save the whole amount.
- The Alabama Housing Finance Authority Step Up program is the best known Alabama option
- Help can come as a grant or a forgivable or repayable second loan, depending on the program
- Income, price, and credit rules apply, so the check happens before house hunting, not after
First-Time Buyer and Jumbo
Two ends of the spectrum, both common in the Huntsville area.
- First-time programs can pair low down payments with assistance and education
- Jumbo loans cover prices above the conforming limit
- Either way, the payment math, the $2,000 lender credit, and the 2/1 buydown on this page still apply
Both calculators, loaded with this home
Both calculators start loaded with 24614 Silent Spring Dr: $332,000, a 0.45% property tax estimate (Alabama taxes are low; confirm the exact figure with the county), and its verified $0 HOA. Change any number and both update. Want the Danmann numbers instead? Type in $229,000.
Full monthly payment
2/1 buydown calculator
Buydown cost is the total principal and interest savings over Years 1 and 2. The $2,000 lender credit can be applied toward that cost. Check any seller paid portion against the program interested party contribution limit for your down payment before you write the offer. That check happens on every scenario before an offer goes in.
Meet Laura Rogers
Laura is a North Alabama native, raised on Smith Lake and based in Madison since 2013. She spent 13 years as a project engineer in the defense industry, grew up around her family's real estate development business, and now sells homes across the Tennessee Valley with eXp Realty The Cinder Group. She is also the host of The American Dream: Selling Alabama. Her published profile puts her at $800K in sales her first year and $3.2 million in 2025, and her focus is first time buyers and families relocating to the Huntsville area.
- Listing agent on both homes on this page, in Athens (MLS #21928982) and Huntsville (MLS #21931751).
- eXp Realty The Cinder Group, 1525 Perimeter Pkwy, Huntsville, AL 35806.
- Alabama License #000160593, Athens State University graduate.
- Reach her direct: call or text 256-464-2111, email laura@thecindergroup.com, or find her on Instagram at @sellinghuntsville_al.
What buyers say about working with Oliver
Borrower reviews from real closed loans, shared by the lending partner on this team.
“Friendly, people oriented and very kind”Verified homebuyer, about Oliver Ames, the mortgage broker on this team
“Communication and follow-through were unmatched”Verified homebuyer, about Oliver Ames, the mortgage broker on this team
One team, start to finish
Two people, one team. Laura handles the home: the search, the showings, the offer, the negotiation. Oliver handles the loan: the numbers, the $2,000 credit, the buydown, the closing. Either one of us can start the conversation.
Laura Rogers
Huntsville, AL 35806
256-464-2111
laura@thecindergroup.com
Alabama License #000160593

Oliver Ames
Personally licensed in AZ & UT.
Me and my team cover 16 states, with select bank-direct programs available nationwide.
$2,000 lender credit for buyers who finance with him.